Understanding Debt Consolidation Loans and Your Home Equity Options
Are high interest rates on credit cards and personal loans making it difficult to get ahead? If you own a home in Urbandale, IA, a debt consolidation mortgage might be the perfect solution to streamline your finances. By tapping into the equity you have built in your property, you can pay off high-interest debts and potentially lower your overall monthly payments.
At The Tyler Osby Team at Fairway Independent Mortgage, we specialize in helping Iowa homeowners explore their debt consolidation options. Whether you are looking for a primary Debt Consolidation Loan, considering a cash-out refinance, or exploring a home equity loan or second mortgage, our team is here to guide you. We are also experts at providing second opinions on debt consolidation mortgages to ensure you are getting the best possible terms for your unique financial situation.
How a Debt Consolidation Mortgage Works
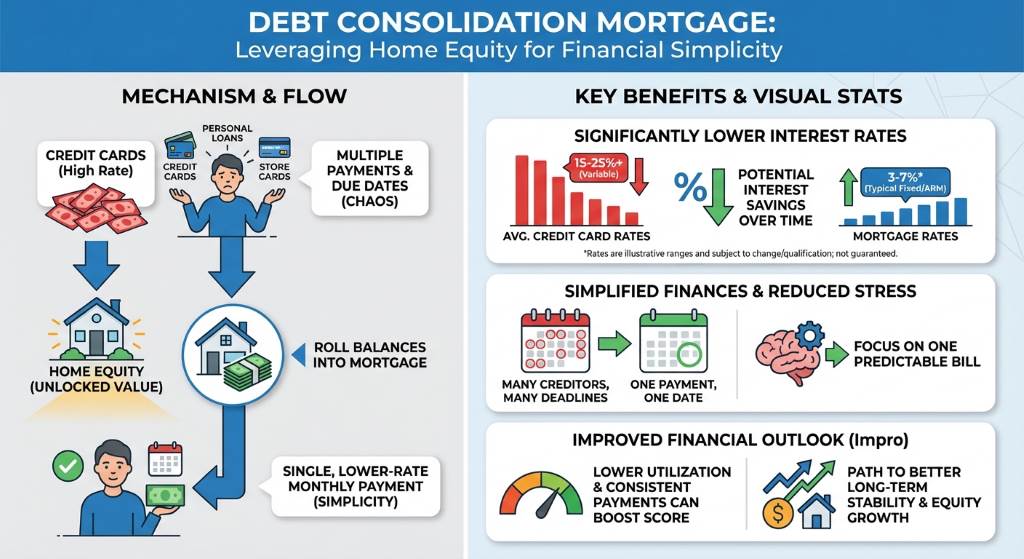
A debt consolidation mortgage allows you to leverage your home equity to pay off other debts. Instead of juggling multiple payments to various creditors, you roll those balances into a single mortgage payment. This approach often comes with a significantly lower interest rate compared to standard credit cards.
- Lower Interest Rates: Mortgages typically offer better rates than unsecured debt.
- Simplified Finances: Make just one payment each month instead of keeping track of several due dates.
- Improved Cash Flow: Extending the repayment term can reduce your monthly obligations, freeing up cash for savings or investments.
It is important to remember that securing debts against your home means your property is collateral. That is why getting expert advice is crucial. If you already have an offer from another lender, reach out to Tyler Osby for a free second opinion. We will crunch the numbers to make sure a debt consolidation mortgage truly benefits your long-term financial health.
| Debt Type | Average Interest Rate | Typical Repayment Term | Monthly Payment Structure |
|---|---|---|---|
| Credit Cards | 18% to 25% | Revolving (Indefinite) | Multiple varying payments |
| Personal Loans | 10% to 15% | 3 to 5 Years | Fixed but higher monthly cost |
| Debt Consolidation Mortgage | 6% to 8% (Market Dependent) | 15 to 30 Years | Single, predictable payment |
Ready to Take Control of Your Financial Future?
Finding the right mortgage in Iowa does not have to be stressful. Tyler Osby is the most recommended mortgage lender in Iowa, boasting over 1,300 five-star reviews. Our team prides itself on transparency, weekly communication, and finding the exact loan product that fits your needs.
Whether you want to consolidate debt, lower your monthly payments, or simply get a professional second opinion on a current loan estimate, we are ready to help. Getting started requires no hard credit inquiry, and we provide a custom home loan report designed specifically for you.
Legal Licensing Information: Fairway Independent Mortgage Corporation, NMLS #2289. Tyler Osby, NMLS #8668, State of Iowa License #19545.
Q1: What is a debt consolidation mortgage?
It is a home loan that allows you to use your home equity to pay off high-interest debts, combining them into one single monthly mortgage payment.
Q2: Can I get a second opinion on my current debt consolidation loan offer?
Absolutely. The Tyler Osby Team specializes in reviewing existing offers to ensure you are getting the most favorable terms and rates available for your situation.
Q3: Will consolidating my debt lower my credit score?
Initially, applying for a new loan may cause a slight, temporary dip in your score. However, paying off maxed-out credit cards and making consistent, on-time mortgage payments can significantly improve your credit score over time.
Q4: What are the alternatives to a cash-out refinance for debt consolidation?
If you do not want to refinance your primary mortgage, you can explore options like a home equity loan or a home equity line of credit (HELOC), which act as a second mortgage.
Q5: How do I know if a debt consolidation mortgage is right for me?
The best way to find out is to schedule a no-obligation consultation. We will evaluate your current debts, your home equity, and your financial goals to determine if this strategy makes sense for you.Apply Online with The Tyler Osby Team Today